Understanding Mutual Funds in Pakistan & Its Mechanics
The Easy Guide For Your Understanding
Mutual Funds in Pakistan provide a wide variety of categories. It has the potential for good gains, but at the same time probability of losses as well.
Ride may be exciting, but it has to be done with fastened seat belts and helmets.
As the name says, 'Mutual', that means Mutual funds are collective investment schemes that people pool money together and give it to a professional institution like banks and other financial companies to create professionally managed, diversified portfolios of securities such as stocks, bonds, and money market instruments.
This structure makes sophisticated investing accessible, liquid, and affordable for individual investors.
The industry in Pakistan is regulated by the Securities & Exchange Commission of Pakistan (SECP), with MUFAP serving as the official trade body.
Funds are operated by Asset Management Companies (AMCs) and the assets are held in custody by a Trustee, ensuring a robust governance framework.
# Mutual Funds in Pakistan: Your Complete Guide to Smart Investing## Everything You Need to Know About Mutual Funds in Pakistan Before You Invest
Let's be honest. Most people in Pakistan keep their savings either in a bank account earning minimal profit or stashed under the proverbial mattress. A smaller group invests in gold or real estate. But there is a growing, smarter, and more accessible way to grow your money that millions of Pakistanis are still sleeping on.
That way is mutual funds in Pakistan.
Whether you are a salaried professional in Karachi, a small business owner in Lahore, an overseas Pakistani sending remittances home, or even a foreigner looking at Pakistan's emerging market potential, mutual funds offer you a structured, regulated, and potentially rewarding way to put your money to work.
This guide will walk you through everything. What mutual funds in Pakistan are, why they exist, their history, types, performance, charges, taxes, risks, and rewards. By the time you finish reading, you will have a clear picture of whether mutual funds deserve a place in your financial life.
Let's dive in.
---
## What Are Mutual Funds? The Simple Explanation
Imagine you and a hundred of your friends each put a certain amount of money into a common pot. You then hire a professional money manager to invest that pot wisely across stocks, bonds, government securities, and other assets. Whatever profits are earned, everyone gets a share proportional to what they put in. And if there are losses, those are shared too.
That, in its simplest form, is a mutual fund.
More formally, a mutual fund is a collective investment scheme that pools money from multiple investors and invests it in a diversified portfolio of securities. The fund is managed by a professional Asset Management Company, commonly called an AMC. Investors buy units of the fund, and the value of those units goes up or down depending on how the underlying investments perform.
The price of each unit is called the Net Asset Value, or NAV. It is calculated daily and tells you exactly what your investment is worth at any given time.
---
## Why Do Mutual Funds in Pakistan Exist? The Rationale
The existence of mutual funds in Pakistan, and everywhere else in the world, is rooted in a few fundamental economic and social realities.
**1. Most people lack the expertise to invest directly.**
Buying stocks or bonds requires research, market knowledge, and time. Most ordinary people do not have these. Mutual funds give them access to professional management.
**2. Diversification reduces risk.**
If you invest all your savings in one company and that company fails, you lose everything. Mutual funds spread money across dozens or hundreds of investments, so one bad apple does not spoil the whole basket.
**3. Small investors deserve access to big markets.**
You might not have enough money to build a diversified stock portfolio on your own. But by pooling resources with thousands of other investors, even a small amount gives you exposure to a wide range of assets.
**4. Liquidity and flexibility.**
Unlike real estate or fixed deposits with lock-in periods, most mutual funds allow you to redeem your investment relatively quickly.
**5. Regulated and transparent.**
Mutual funds in Pakistan are regulated by the Securities and Exchange Commission of Pakistan, the SECP. This provides a layer of investor protection that informal investment schemes simply do not offer.
---
## A Brief History of Mutual Funds in Pakistan
The story of mutual funds in Pakistan is actually older than most people realize.
**The Early Beginnings: 1962**
The first mutual fund in Pakistan was the Investment Corporation of Pakistan, established in 1966, but the groundwork was laid even earlier. The National Investment Trust, known as NIT, was established in 1962 and is considered the pioneer of mutual funds in Pakistan. NIT was a government-backed fund designed to give ordinary Pakistanis access to the stock market. For decades, NIT was essentially the only game in town for retail investors interested in collective investment.
**The Investment Corporation of Pakistan: 1966**
The Investment Corporation of Pakistan, or ICP, was set up in 1966 to further develop the capital markets and provide investment opportunities. ICP launched a series of mutual funds over the years and played a significant role in the early development of the industry.
**Privatization and Private Sector Entry: 1990s**
The real transformation of mutual funds in Pakistan began in the 1990s when the government started liberalizing the financial sector. Private asset management companies began entering the market. This brought competition, innovation, and a much wider range of fund options for investors.
**The NBFC Rules and SECP Regulation: 2000s**
A major milestone came when the SECP introduced the Non-Banking Finance Companies Rules in 2003 and later the NBFC and Notified Entities Regulations in 2008. These regulations formalized the industry, set standards for fund management, and significantly improved investor protection.
**Rapid Growth: 2010 to Present**
The past decade has seen remarkable growth in mutual funds in Pakistan. The number of AMCs has grown significantly. The variety of funds has expanded dramatically. And the total Assets Under Management, or AUM, of the mutual fund industry has grown from a few hundred billion rupees to over Rs. 2 trillion and counting.
As of recent data from the Mutual Funds Association of Pakistan, known as MUFAP, the industry manages assets worth well over Rs. 2 trillion, with dozens of AMCs and hundreds of individual fund options available to investors.
---
## Types of Mutual Funds in Pakistan
One of the most attractive features of mutual funds in Pakistan is the sheer variety available. There is genuinely something for every type of investor, whether you are extremely cautious or willing to take on more risk for higher returns.
Here are the main types:
### 1. Money Market Funds
These are the safest and most liquid type of mutual funds in Pakistan. They invest in short-term government securities, treasury bills, and bank deposits. They are ideal for parking money you might need soon or for very conservative investors.
- Low risk
- Returns typically between 18% to 22% per annum in recent high-interest-rate environments
- High liquidity, usually redeemable within one to two business days
### 2. Income Funds
Income funds invest primarily in fixed-income securities like government bonds, Pakistan Investment Bonds, corporate bonds, and term finance certificates. They aim to provide regular income with moderate risk.
- Low to moderate risk
- Returns generally slightly higher than money market funds
- Suitable for investors seeking steady income
### 3. Equity Funds
These funds invest primarily in stocks listed on the Pakistan Stock Exchange. They carry higher risk but offer the potential for significantly higher long-term returns.
- Higher risk
- Potential for returns of 20% to 40% or more in good market years
- Best suited for investors with a long-term horizon of three to five years or more
### 4. Balanced Funds
As the name suggests, balanced funds invest in a mix of equities and fixed-income securities. They aim to provide a balance between growth and income.
- Moderate risk
- Moderate returns
- Good for investors who want some growth but are not comfortable with full equity exposure
### 5. Islamic or Shariah-Compliant Funds
Pakistan has a large Muslim population with a strong preference for Shariah-compliant investments. Islamic mutual funds in Pakistan invest only in assets that comply with Islamic principles. They avoid interest-based instruments and prohibited industries.
- Available across all categories: Islamic money market, Islamic income, Islamic equity, and Islamic balanced funds
- Regulated and certified by Shariah advisors
- Increasingly popular and now represent a significant portion of total industry AUM
### 6. Fund of Funds
These are funds that invest in other mutual funds rather than directly in securities. They offer an additional layer of diversification.
### 7. Index Funds
Index funds track a specific market index, such as the KSE-100. They are passively managed, meaning lower fees, and aim to replicate the performance of the index.
### 8. Capital Protected Funds
These funds aim to protect the investor's principal while still offering some upside potential. They are structured products with specific maturity dates.
### 9. Voluntary Pension Schemes (VPS)
While technically a separate category, Voluntary Pension Schemes operate similarly to mutual funds and are managed by AMCs. They are specifically designed for retirement savings and offer significant tax benefits.
---
## Major Asset Management Companies in Pakistan
Several reputable AMCs manage mutual funds in Pakistan. Some of the prominent names include:
- **Meezan Asset Management** (largest Islamic AMC)
- **Al Meezan Investments**
- **NBP Funds**
- **UBL Fund Managers**
- **HBL Asset Management**
- **MCB-Arif Habib Savings and Investments**
- **Alfalah Asset Management**
- **Faysal Asset Management**
- **JS Investments**
- **Atlas Asset Management**
Each of these companies offers a range of funds across different categories and risk profiles.
---
## Past Performance of Mutual Funds in Pakistan
Past performance is never a guarantee of future results, but it does provide useful context.
**Money Market Funds** have been among the standout performers in recent years, largely because of Pakistan's high interest rate environment. With the State Bank of Pakistan's policy rate reaching as high as 22% in 2023 and 2024, money market funds were delivering annualized returns in the range of 18% to 22%, which is exceptional by any standard.
**Equity Funds** have had a more volatile history, as you would expect. The KSE-100 index has seen dramatic swings over the years. However, over long periods, equity funds have delivered strong returns. The KSE-100 has been one of the best-performing stock markets in Asia over certain multi-year periods. Investors who stayed the course through the ups and downs have generally been rewarded.
**Islamic Funds** have grown enormously in popularity and have largely matched or in some cases outperformed their conventional counterparts, particularly in the equity space.
**Balanced Funds** have provided middle-ground performance, offering reasonable returns with lower volatility than pure equity funds.
---
## Current Rates and Returns on Mutual Funds in Pakistan
As of 2024 and into 2025, here is a general picture of returns across different fund categories. Please note these are approximate figures and change frequently:
- **Money Market Funds:** Approximately 18% to 22% annualized
- **Income Funds:** Approximately 17% to 21% annualized
- **Equity Funds:** Variable, but the KSE-100 has shown strong performance in 2024, with many equity funds delivering returns of 30% to 60% or more in strong bull market years
- **Islamic Money Market Funds:** Approximately 17% to 21% annualized
- **Balanced Funds:** Approximately 20% to 35% depending on equity allocation
It is important to check the latest NAV and fund fact sheets directly from the AMC or from MUFAP's website for the most current figures.
---
## Charges and Fees on Mutual Funds in Pakistan
Like any financial product, mutual funds in Pakistan come with certain costs. Understanding these is important for calculating your actual net return.
**Management Fee**
This is the annual fee charged by the AMC for managing the fund. It typically ranges from 0.5% to 3% of the fund's assets per year, depending on the fund type. Equity funds generally have higher management fees than money market funds.
**Front-End Load**
Some funds charge a fee when you invest, called a front-end load or sales load. This can range from 0% to 3% of your investment amount. Many AMCs have reduced or eliminated front-end loads to attract investors.
**Back-End Load**
Some funds charge a fee when you redeem your investment, particularly if you redeem before a certain period. This is called a back-end load or redemption fee.
**Trustee Fee**
A small fee paid to the trustee, usually a bank, that holds the fund's assets in custody. This is typically around 0.1% to 0.2% per year.
**Sindh Sales Tax on Management Fee**
Sindh Sales Tax is applicable on the management fee charged by AMCs. This is typically 13% of the management fee.
**Other Expenses**
These include audit fees, legal fees, and other administrative costs, which are usually very small.
The good news is that all these charges are disclosed in the fund's offering document and are reflected in the NAV calculation. You can always see the total expense ratio, or TER, for each fund, which gives you a clear picture of the total annual cost.
---
## Taxes on Mutual Funds in Pakistan
Tax treatment is an important consideration for any investor. Here is how mutual funds in Pakistan are taxed:
**Capital Gains Tax (CGT)**
- For stock funds (equity funds), capital gains are taxed at 12.5% if held for less than one year and 10% if held for more than one year.
- For other funds, the CGT rate depends on the holding period and the investor's tax status.
**Dividend Income**
- Dividends distributed by mutual funds are subject to withholding tax. For filers, the rate is generally 15%. For non-filers, it can be higher.
**Voluntary Pension Schemes (VPS) Tax Benefits**
- Contributions to VPS are deductible from taxable income up to 20% of your annual income (for individuals under 40) or higher percentages for older investors. This is one of the most significant tax benefits available to Pakistani investors.
**Zakat**
- Zakat is deducted on the redemption value of mutual fund units if the investor is a Muslim and has not submitted a Zakat exemption form.
It is always advisable to consult a tax advisor for your specific situation, as tax laws in Pakistan can change and individual circumstances vary.
---
## Investing in Mutual Funds in Pakistan: Who Can Invest?
### Pakistani Residents
Any Pakistani citizen with a valid CNIC can invest in mutual funds in Pakistan. The process has become incredibly simple. Most AMCs now offer online account opening. You can start investing with as little as Rs. 500 to Rs. 1,000 in many funds. There is no upper limit.
### Overseas Pakistanis
This is where things get particularly exciting. Overseas Pakistanis can invest in mutual funds in Pakistan using their NICOP or Pakistan Origin Card. Many AMCs have specifically designed platforms and processes to facilitate overseas Pakistani investors. Roshan Digital Account, launched by the State Bank of Pakistan, has also made it significantly easier for overseas Pakistanis to invest in Pakistan's financial markets, including mutual funds.
The potential here is enormous. Overseas Pakistanis send over $25 billion in remittances to Pakistan annually. Even a fraction of that channeled into mutual funds could transform both individual wealth and the broader economy.
### Foreigners
Foreign nationals can also invest in mutual funds in Pakistan, subject to certain regulatory requirements. They need to open a Special Convertible Rupee Account, or SCRA, through a Pakistani bank. The process is more involved than for Pakistani nationals, but it is possible and legal. Given Pakistan's high interest rates and the potential for strong equity market returns, some foreign investors do find Pakistan's mutual fund market attractive.
---
## The Potential of Mutual Funds in Pakistan
The growth potential of mutual funds in Pakistan is genuinely exciting, and here is why:
**Low Penetration Rate**
Despite years of growth, mutual fund penetration in Pakistan remains very low compared to regional peers. In India, for example, mutual fund AUM is over 60% of GDP. In Pakistan, it is a tiny fraction of that. This means there is enormous room for growth.
**Young Population**
Pakistan has one of the youngest populations in the world. Young people who start investing early in mutual funds benefit enormously from the power of compounding over time.
**Digital Revolution**
Mobile banking and fintech platforms are making it easier than ever to invest. Apps like Meezan Bank's digital platform, UBL's digital services, and dedicated investment apps are bringing mutual funds to millions of new investors who previously had no access.
**High Returns in Current Environment**
With interest rates historically high and the stock market showing strong momentum, the current environment offers compelling return opportunities across multiple fund categories.
**Roshan Digital Account**
The Roshan Digital Account initiative has been a game changer for overseas Pakistanis. It allows them to invest in Naya Pakistan Certificates and increasingly in mutual funds, making it easier to participate in Pakistan's financial markets from anywhere in the world.
---
## What Credible Authorities and Experts Say About Mutual Funds in Pakistan
The endorsement of mutual funds in Pakistan from credible quarters is strong and consistent.
**The Securities and Exchange Commission of Pakistan (SECP)**
The SECP has consistently promoted mutual funds as a safe, regulated, and accessible investment vehicle for retail investors. The SECP has worked to strengthen regulations, improve transparency, and protect investor rights in the mutual fund industry.
**The Mutual Funds Association of Pakistan (MUFAP)**
MUFAP, the industry body, regularly publishes data showing the growth and performance of the industry. MUFAP CEO and officials have repeatedly highlighted the potential for mutual funds to become a mainstream savings and investment vehicle for Pakistani households.
**State Bank of Pakistan**
The SBP has supported the development of capital markets, including mutual funds, as part of its broader financial inclusion
Salient Points of Mutual Funds in Pakistan
Some key salient points include:
- Structure and Types: Funds are primarily classified as open-ended (units bought/redeemed on demand at Net Asset Value) or closed-ended (fixed shares traded on a stock exchange). The SECP further categorizes funds by investment strategy, including Equity, Income, Balanced, Shariah Compliant, and Money Market schemes, catering to varied risk appetites and investment horizons.
- Investor Benefits: The primary advantages are professional management, risk reduction through diversification, high liquidity allowing conversion to cash on any working day, and accessibility for small investors.
- Taxation Incentives: The framework offers significant tax benefits. Individual investors can claim a tax credit under Section 62 of the Income Tax Ordinance, 2001. Furthermore, Capital Gains Tax (CGT) is structured to reward long-term investment, with a 0% rate for securities held for 24 months or more.
- Regulatory Oversight: The SECP provides stringent oversight through licensing, continuous monitoring via mandatory reporting, and on-site inspections of AMCs, ensuring investor protection and market integrity.
Framework for The Mutual Funds in Pakistan
The core mechanism behind the mutual funds in Pakistan involves investors entrusting their money to an Asset Management Company (AMC).
The AMC's professional fund managers then invest this pooled capital into securities like stocks, bonds, and money market instruments.
The returns generated from these investments, including income and capital appreciation, are then distributed back to the investors (unit holders) in proportion to their ownership.
Regulatory and Operational Structure
The good part is that the Mutual Fund industry in Pakistan operates under a well-defined regulatory structure involving several key entities:
- Mutual Funds Association of Pakistan (MUFAP): The government-licensed trade body for the mutual fund industry. All AMCs and Investment Advisory services licensed by the SECP are required to be members.
- Securities & Exchange Commission of Pakistan (SECP): The primary regulator of the mutual funds industry. The SECP is responsible for issuing licenses for Collective Investment Schemes (CIS), approving fund establishments, and conducting continuous monitoring through regular reports and on-site inspections of AMCs.
- Asset Management Companies (AMCs): Public limited companies registered under the Companies Ordinance, 1984, that operate and manage mutual funds. An AMC launches a new fund by establishing a Trust Deed.
- Trustee: A custodian of the fund's assets, responsible for ensuring that the Fund Manager's investment decisions align with the fund's stated investment policy. Under Pakistani law, banks and central depository companies approved by the SECP can act as trustees. The Central Depository Company of Pakistan (CDC) currently serves as the trustee for most funds in the industry.
The establishment of a Mutual Fund requires a Trust Deed entered into between the AMC and the Trustee, which must receive due approval from the SECP under the Non-Banking Finance Companies (Establishment and Regulation) Rules, 2003.
Types and Categories of Mutual Funds In Pakistan
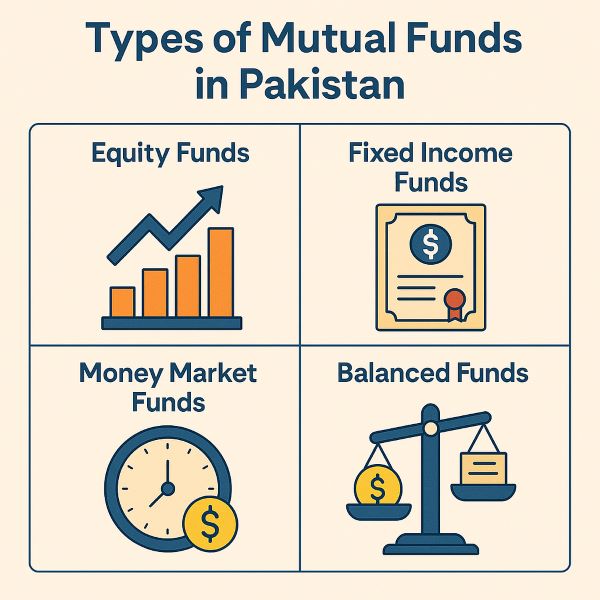
Mutual funds in Pakistan are classified based on their structure and their investment objectives as categorized by the SECP.
Structural Classification
- Open-Ended Mutual Funds (Unit Trusts): These funds continually create new units for investors to buy or redeem existing units on demand. Unit holders can buy or sell units on a continuous basis directly from the Management Company at the prevailing Net Asset Value (NAV).
- Closed-Ended Mutual Funds: These funds issue a fixed number of shares through an Initial Public Offering (IPO). After issuance, these shares are traded on the secondary market (Stock Exchange) at market rates, similar to the shares of a public company.
SECP Investment Categories
The SECP has categorized mutual fund schemes to reflect their investment strategies and objectives:
Equity Scheme invests primarily in stocks (equities) with the objective of long-term growth through capital appreciation.
Balanced Scheme invests in a mix of stocks and debt instruments to provide a balance of growth and income.
Asset Allocation Fund diversifies assets across multiple security types and investment styles available in the market.
Fund of Fund Scheme invests in a portfolio of other mutual funds (equity, balanced, fixed income, etc.).
Shariah Compliant (Islamic) Scheme invests only in Shariah-compliant securities (shares, Sukuk, Ijara sukuks) as approved by a Shariah Advisor.
Capital Protected Scheme guarantees the return of the original investment amount, plus any potential capital gains, at the end of a specific contractual term.
Index Tracker Scheme aims to mirror the performance of a market index, such as the KSE 100, by holding securities in the same proportion as the index.
Money Market Scheme is one of the safest fund types, investing in short-term debt instruments like Treasury bills and bank deposits.
Income Scheme focuses on providing a steady stream of income by investing in short and long-term debt instruments like TFCs and government securities.
Aggressive Fixed Income Scheme seeks to generate high returns by investing in fixed-income securities, including those of medium to lower quality.
Commodity Scheme enables investment in commodities like gold by investing at least 70% of assets in commodity futures contracts.
Key Investor Benefits for Investing in Mutual Funds in Pakistan
Investing in mutual funds in Pakistan offers several distinct advantages, particularly for individual investors.
- Accessibility: Mutual fund units are simple and easy to purchase.
- Liquidity: Unit holders can convert their investments into cash on any working day by redeeming their units with the fund itself, which then pays out the current value promptly.
- Diversification: By pooling money, a mutual fund invests in a wide array of securities, which spreads and reduces investment risk. Achieving a similar level of diversification would be difficult for an average investor with limited capital.
- Professional Management: AMCs employ expert fund managers who evaluate market opportunities and make informed investment decisions, a task that can be complex for individuals or non-financial corporate entities.
Investment Mechanics and Valuation
Mostly, Mutual Fund performance rests on the main KPI, i.e., NAV (Net Asset Value - Daily Basis)
- Calculating Unit Price (Net Asset Value - NAV)
The price per unit of a mutual fund is represented by its Net Asset Value (NAV). It is calculated daily using the following formula:
- NAV = (Current Market Value of all Assets – Liabilities) / Total Number of Units Outstanding
The sale price of a unit is determined by adding a sales load to the NAV. If there is no sales load, the NAV serves as both the sale and redemption price.
Investment and Disinvestment Process in Mutual Funds in Pakistan
How to Invest in Mutual Funds in Pakistan
- Individuals: Must provide a copy of their CNIC, a completed Application/Account Opening Form, a Purchase of Units Form, and optional Zakat Affidavit, along with KYC and FATCA forms. Investment is made via a cheque in favor of the fund's Trustee.
- Corporate/Institutional Investors: Must provide foundational documents (e.g., Memorandum and Articles of Association, Trust Deed), a Board/Trustee resolution authorizing the investment, relevant forms, a Power of Attorney for the authorized officer, NTN, and a cheque.
How to Disinvest (Redeem): An investor can redeem units by submitting a Redemption Form at a designated sales point of the AMC. The redemption payment is processed within a maximum of six working days and paid via a cross-cheque or bank transfer.
Dividend Payments
Dividends can be paid out in cash on a monthly, quarterly, or annual basis, depending on the fund. Investors also have the option to inform the AMC to reinvest the dividend amount, in which case new units are issued instead of a cash payment.
Taxation Framework for Mutual Funds in Pakistan
The tax regime for mutual funds in Pakistan includes incentives for individual investors and specific tax rates for dividend income and capital gains.
NOTE: These can change from time to time in accordance with government policy. You must check with your Mutual Fund Operator for the updated policies.
However, some taxation information is provided below:
Tax Credit for Individual Investors (Section 62)
Under Section 62 of the Income Tax Ordinance, 2001, a resident individual taxpayer is entitled to a tax credit on investments in new shares of a listed public company, which includes units of mutual funds.
- Eligibility: The tax credit is available on the lower of:
- The actual cost of the investment.
- 20% of the individual's taxable income for the year.
- Rs. 1 million.
- Holding Period: The investment must be held for at least 24 months from the date of acquisition. If disposed of within this period, the tax credit availed must be paid back.
Tax Credit Examples for Salaried Individuals
Annual Taxable Income (Upper Limits): PKR 750,000
- Average Tax Rate: 5%
- Gross Tax Payable: PKR 35,000
- Investment for Tax Credit (20% of Income): PKR 150,000
- Tax Credit Available Tax Saving (% of Investment): PKR 7000
- Tax Savings (% of investment): 4.7%
Annual Taxable Income (Upper Limits): PKR 1,500,000
- Average Tax Rate: 10%
- Gross Tax Payable: PKR 147,500
- Investment for Tax Credit (20% of Income): PKR 300,000
- Tax Credit Available Tax Saving (% of Investment):PKR 29,500
- Tax Savings (% of investment): 9.8%
Annual Taxable Income (Upper Limits): PKR 2,500,000
- Average Tax Rate: 14%
- Gross Tax Payable: PKR 347,500
- Investment for Tax Credit (20% of Income): PKR 500,000
- Tax Credit Available Tax Saving (% of Investment): PKR 69,500
- Tax Savings (% of investment): 13.9%
Annual Taxable Income (Upper Limits): PKR 4,000,000
- Average Tax Rate: 18%
- Gross Tax Payable: PKR 722,500
- Investment for Tax Credit (20% of Income): PKR 800,000
- Tax Credit Available Tax Saving (% of Investment): PKR 144,500
- Tax Savings (% of investment): 18.1%
Annual Taxable Income (Upper Limits): PKR 6,000,000
- Average Tax Rate: 22%
- Gross Tax Payable: PKR 1,322,500
- Investment for Tax Credit (20% of Income): PKR 1,000,000
- Tax Credit Available Tax Saving (% of Investment): PKR 220,417
- Tax Savings (% of investment): 22%
Note: Maximum investment eligible for tax credit is restricted to Rs. 1 million.
Tax Credit Examples for Self-Employed Individuals:
Annual Taxable Income (Upper Limits): PKR 750,000
- Average Tax Rate Gross Tax:2%
- Gross Tax Payable: PKR 17,500
- Payable Investment for Tax Credit (20% of Income): PKR 150,000
- Tax Credit Available: PKR 3500
- Tax Saving (% of Investment): 2.3%
Annual Taxable Income (Upper Limits): PKR 1,500,000
- Average Tax Rate Gross Tax:6%
- Gross Tax Payable: PKR 95,000
- Payable Investment for Tax Credit (20% of Income): PKR 300,000
- Tax Credit Available: PKR 19,000
- Tax Saving (% of Investment): 6.3%
Annual Taxable Income (Upper Limits): PKR 2,500,000
- Average Tax Rate Gross Tax:11%
- Gross Tax Payable: PKR 262,500
- Payable Investment for Tax Credit (20% of Income): PKR 500,000
- Tax Credit Available: PKR 52,500
- Tax Saving (% of Investment): 10.5%
Annual Taxable Income (Upper Limits): PKR 4,000,000
- Average Tax Rate Gross Tax:15%
- Gross Tax Payable: PKR 600,000
- Payable Investment for Tax Credit (20% of Income): PKR 800,000
- Tax Credit Available: PKR 120,000
- Tax Saving (% of Investment): 15%
Annual Taxable Income (Upper Limits): PKR 7,000,000
- Average Tax Rate Gross Tax:20%
- Gross Tax Payable: PKR 1,425,000
- Payable Investment for Tax Credit (20% of Income): PKR 1,000,000
- Tax Credit Available: PKR 203,571
- Tax Saving (% of Investment): 20.4%
Note: Maximum investment eligible for tax credit is restricted to Rs. 1 million.
Withholding Tax on Dividend Income
Fund Type: Stock Fund
- Recipient: All recipients (if dividend receipts < capital gains)
- Tax Rate: 12.5%
Fund Type: All Other Mutual Funds
- Recipient: Banks and Companies
- Tax Rate: 25%
Fund Type: All Other Mutual Funds
- Recipient: Individuals and other unit holders
- Tax Rate: 10% for filers, 15% for non-filers
Capital Gains Tax (CGT)
Mutual funds are required to withhold Capital Gains Tax based on the holding period of the security.
- Holding Period Less than twelve months: 12.5%
- Holding Period Twelve months to less than twenty-four months: 10%
- Holding Period Twenty-four months or more: 0%
Wrap up On Mutual Funds in Pakistan
Mutual Funds in Pakistan offer good investment schemes, but it has its own risks and rewards.
It is always advised that one should invest cautiously and check your own risk appetite.
If you don't have the internal capacity to incur losses, then you should choose the capital guaranteed income funds.
The difference between risk and reward is the return rate.
When you choose the capital guaranteed funds, then you will almost get the normal bank savings rates, which may range from 5-10%
On the other hand, if you do have an appetite to take some risks, then you can choose the fund that invests in shares and stocks.
In good times in stock markets (equity market), you can get about 20-40% annual return on your money. But you may also lose the same amount 20-40% of your money, in bad economic times and during the market crashes.
Overall, Mutual Funds in Pakistan and globally are professionally managed funds by big-league companies. The Security of money and trading is very much regulated. However, the promise of returns may vary depending on the type of Fund selection.
You can also learn more about mutual funds in Pakistan here
STAFF WRITER
IdeasBeat is primarily a Marketing Consultancy for Micro Small, & Medium Enterprises (MSMEs) with key focus on digital and content marketing. At the same time, we bring insightful and inspiring stories from all around the world to make you unwind too. We share easy-to-digest articles, ebooks and curated content from selected sources globally.
Risk Disclaimer
All investments in mutual funds are explicitly subject to market risks. The Net Asset Value (NAV) of units can fluctuate, either rising or falling, based on prevailing market conditions. Past performance is not a reliable indicator of future results. Investors are strongly advised to read the fund's Offering Document carefully, paying close attention to the investment policies, risk disclosures, and warning statements before making an investment decision.